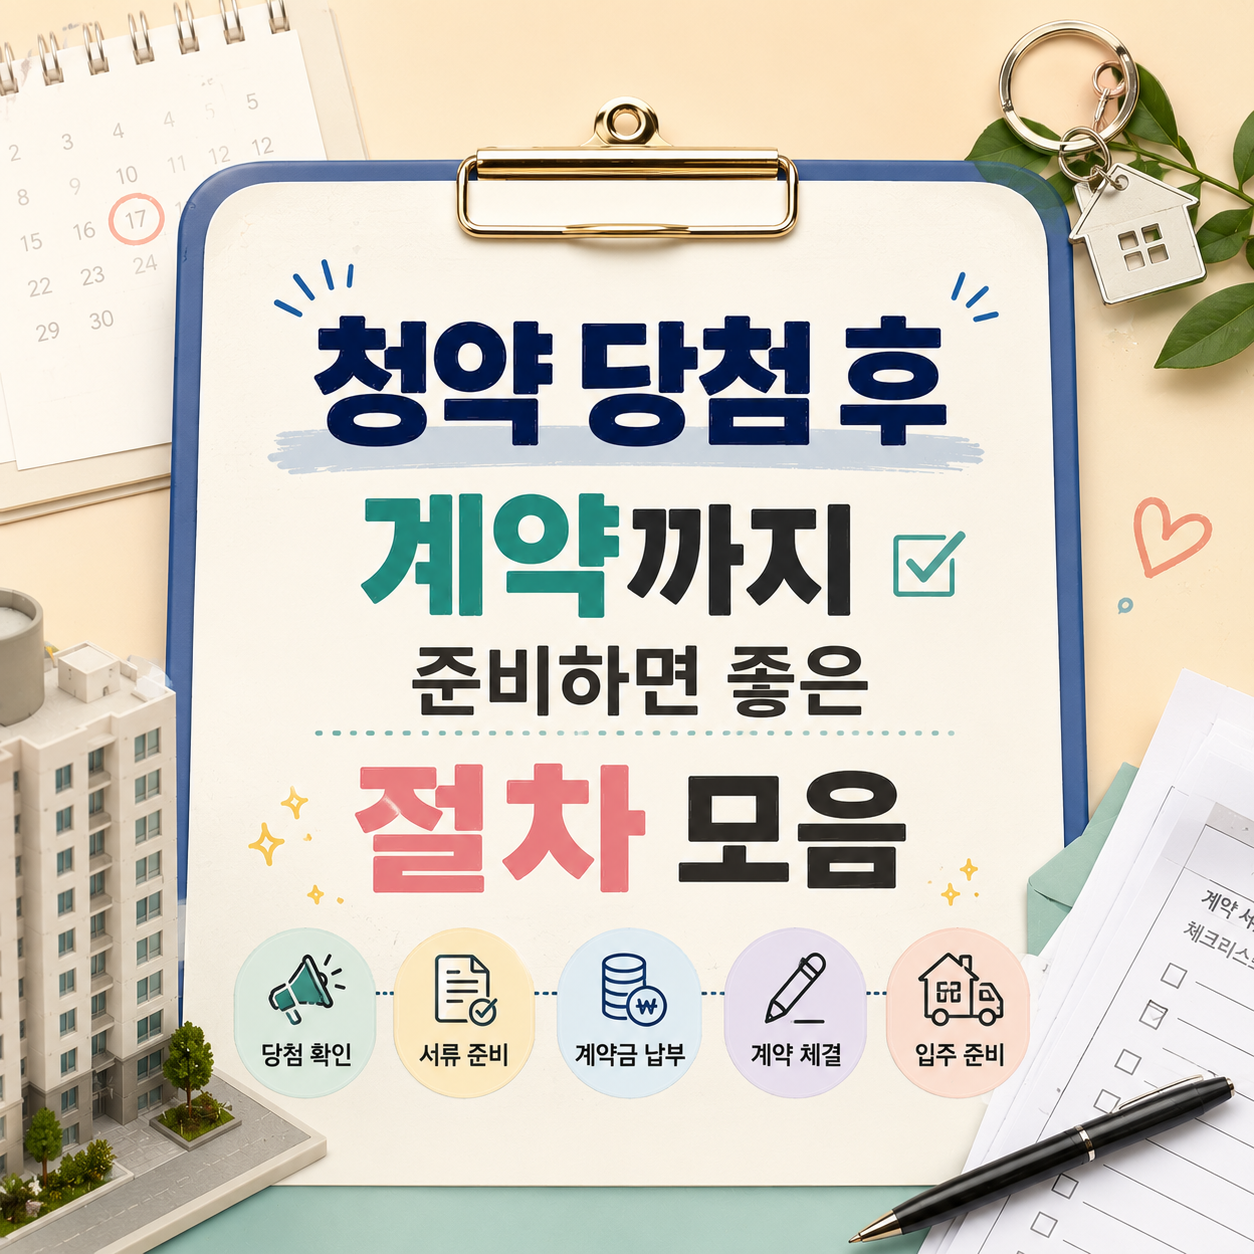
Winning a housing subscription lottery in Korea is just the start of a paperwork and financing process — here is the order to follow, from result confirmation to move-in funds.
Winning a housing subscription draw does not mean the process is over, it means a new one is starting. Within a set window, winners have to verify eligibility, arrange financing in stages, and sign a contract, and missing a single deadline can cost a hard-won chance entirely.
This list walks through the actual order winners have to follow, from checking the result to lining up move-in funds. It focuses on the points that trip people up right after winning: when eligibility documents are due, how the down payment and mid-term loan fit together, and what penalties apply if a contract gets canceled. If you just confirmed you won, start at rank 1; if documents are already filed, jump to rank 4 for the down payment.
How this list was built
- Ordered to match the actual sequence winners go through after the announcement
- Weighted toward steps with tight deadlines, since those are the easiest to miss
- Written on the assumption that region- and complex-specific rules should be confirmed through official channels
Check the Winner Announcement
Submit Eligibility Documents
Confirm You Are Not Disqualified
Prepare the Down Payment
Review the Sale Contract
Apply for Mid-Term Loans
Plan the Balance Payment and Move-In Funds
Understand Contract Cancellation Penalties
How to plan it out
Once you confirm the result, open the official listing notice right away and note the document deadline and contract date. If documents are already filed, the next move is mapping out the full cash flow from down payment through mid-term loan to the final balance, which is the surest way to avoid canceling later for lack of funds.
Loan terms and payment schedules differ by complex, so use this order as a guide but decide based on the listing notice and Cheongyak Home. Ranks 6 and 7, the mid-term loan and the balance payment, depend heavily on personal credit and income, so it is worth checking with a lender before signing.
This guide reflects information as of September 2026, and subscription rules and lending regulations change often, so confirm the latest details through Cheongyak Home and the relevant financial institution before signing a contract or applying for a loan.
Frequently asked questions
How long do I have to submit documents after winning?
Deadlines vary by supply type and complex, and are announced alongside the winner notice, so check the official listing notice and Cheongyak Home for the exact date. Missing the deadline can carry real consequences, so it is best to check immediately after the announcement.
Is a mid-term loan guaranteed once I win?
No. Each complex has its own designated lenders and guarantee conditions, and actual approval depends on individual credit and existing debt, so terms can vary. It is safer to confirm loan conditions directly with a lender before signing the contract.
What happens if I cancel the contract?
Depending on the complex, supply type, and region, canceling can lead to a temporary subscription ban or restrictions on your subscription account. Check the developer's notice and Cheongyak Home for the exact penalty that applies.
What should I do if I get disqualified?
Start by checking the response window and required materials listed in the disqualification notice. It usually comes from a mismatch between the self-reported application and the actual documents, so if anything is unclear, contact the developer or Cheongyak Home directly rather than guessing.
What should I check carefully in the sale contract?
Paid options, balcony extension costs, the mid-term payment schedule, expected move-in date, and cancellation terms can differ from what a model-house agent described, so read the actual wording before signing. Also confirm the unit number, floor area, and price match the original application.
Get new lists before anyone else
Once a week — only the new lists worth your time.
No spam · unsubscribe in one click
You may also like
Public Housing & NewHome Subscription Types in Korea, Explained
A plain-language guide to Korea's public housing and NewHome subscription types, covering what to verify before applying.
A Checklist for the Confusing Parts of Housing Subscription Scoring
A checklist of the items people commonly miscalculate in housing subscription scoring, including years without a home, dependent count, and subscription account tenure.